Indian customers have moved to digital banking at remarkable speed. Account opening, loan applications, credit card sign-ups and service requests that once needed a branch visit now happen on a phone. But a digital journey that looks smooth in a product demo can feel very different to a real customer on a patchy connection, juggling documents and OTPs.
What is digital customer journey mapping?
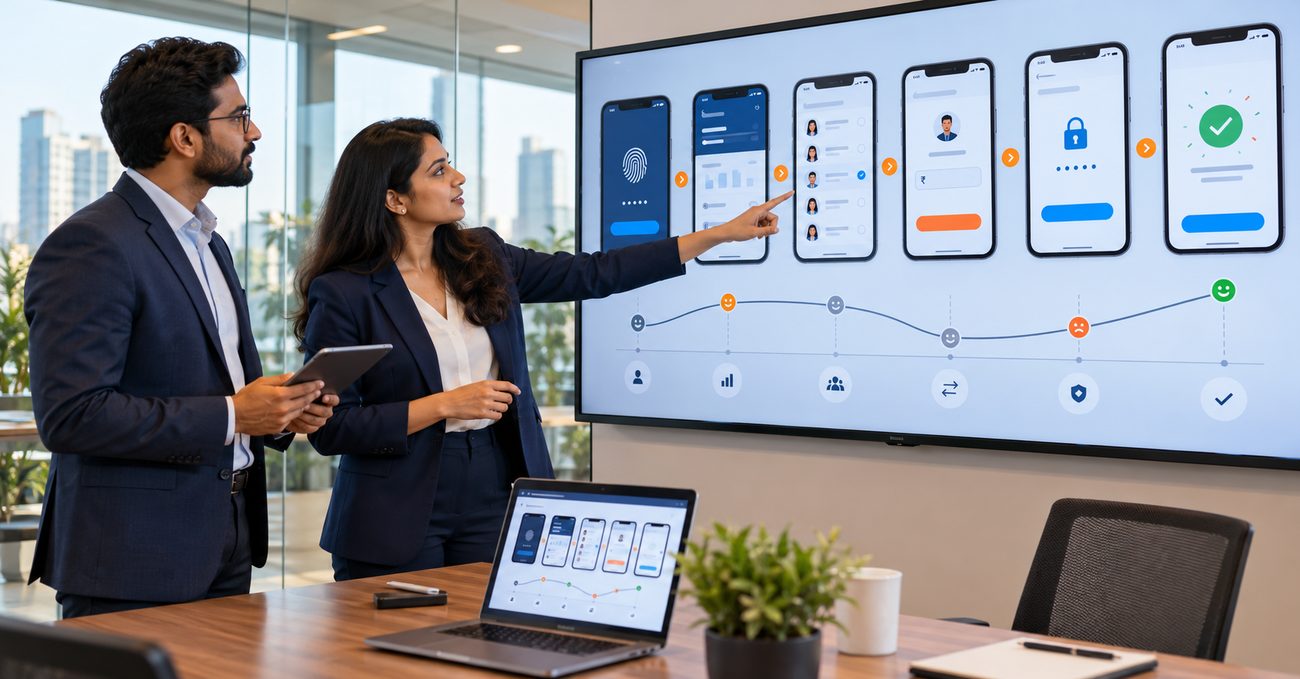
Digital customer journey mapping applies the principles of journey mapping to online channels: apps, websites, chat, email and SMS. It tracks a customer step by step through a digital process, recording every screen, field, message and wait, along with the customer’s thoughts and frustrations.
Where digital banking journeys break
Across digital banking journeys, the same friction points come up again and again:
-
Long forms that ask for information the bank already has
-
Document upload failures with unclear error messages
-
OTP and verification loops that time out or have to be repeated
-
Video KYC scheduling that leaves customers waiting without updates
-
Silent waits after submission, with no status tracking
-
Channel switches where the customer is pushed to call or visit a branch to finish
Each one is a point where customers abandon the process, often without the bank ever knowing why.
How digital journey mapping works
A strong digital mapping exercise combines several methods:
-
Digital mystery shopping: Trained evaluators complete the real application journey, recording every step, delay and error on different devices and networks.
-
Competitor walkthroughs: The same journey is completed with competing banks to benchmark speed, clarity and effort.
-
Analytics review: Drop-off data shows where customers leave, and the mapping shows why.
-
Customer feedback: Interviews and surveys add the customer’s own words and emotions.
Example: a credit card application
A typical mapped journey might run from ad click to landing page, eligibility check, application form, document upload, video KYC, approval, card dispatch, activation and first use. Mapping often reveals that the biggest drop-offs aren’t in the form itself but in the waiting stages, where customers hear nothing for days and assume they’ve been rejected.
Turning the map into improvements
The output should be a prioritised list of fixes: shorter forms, pre-filled fields, clearer error messages, proactive status updates, and fewer forced channel switches. Small changes at high-drop-off moments often deliver the biggest gains.
Why it matters
For banks, digital journeys are now the front door. A smooth journey wins customers at lower cost. A frustrating one sends them to a competitor in a few taps. Mapping it properly is one of the most direct ways to protect both acquisition and reputation.
Want this evidence for your brand? Talk to our team about a study scoped to your customers, channels and goals, or write to growth@bridgeloyalty.com.