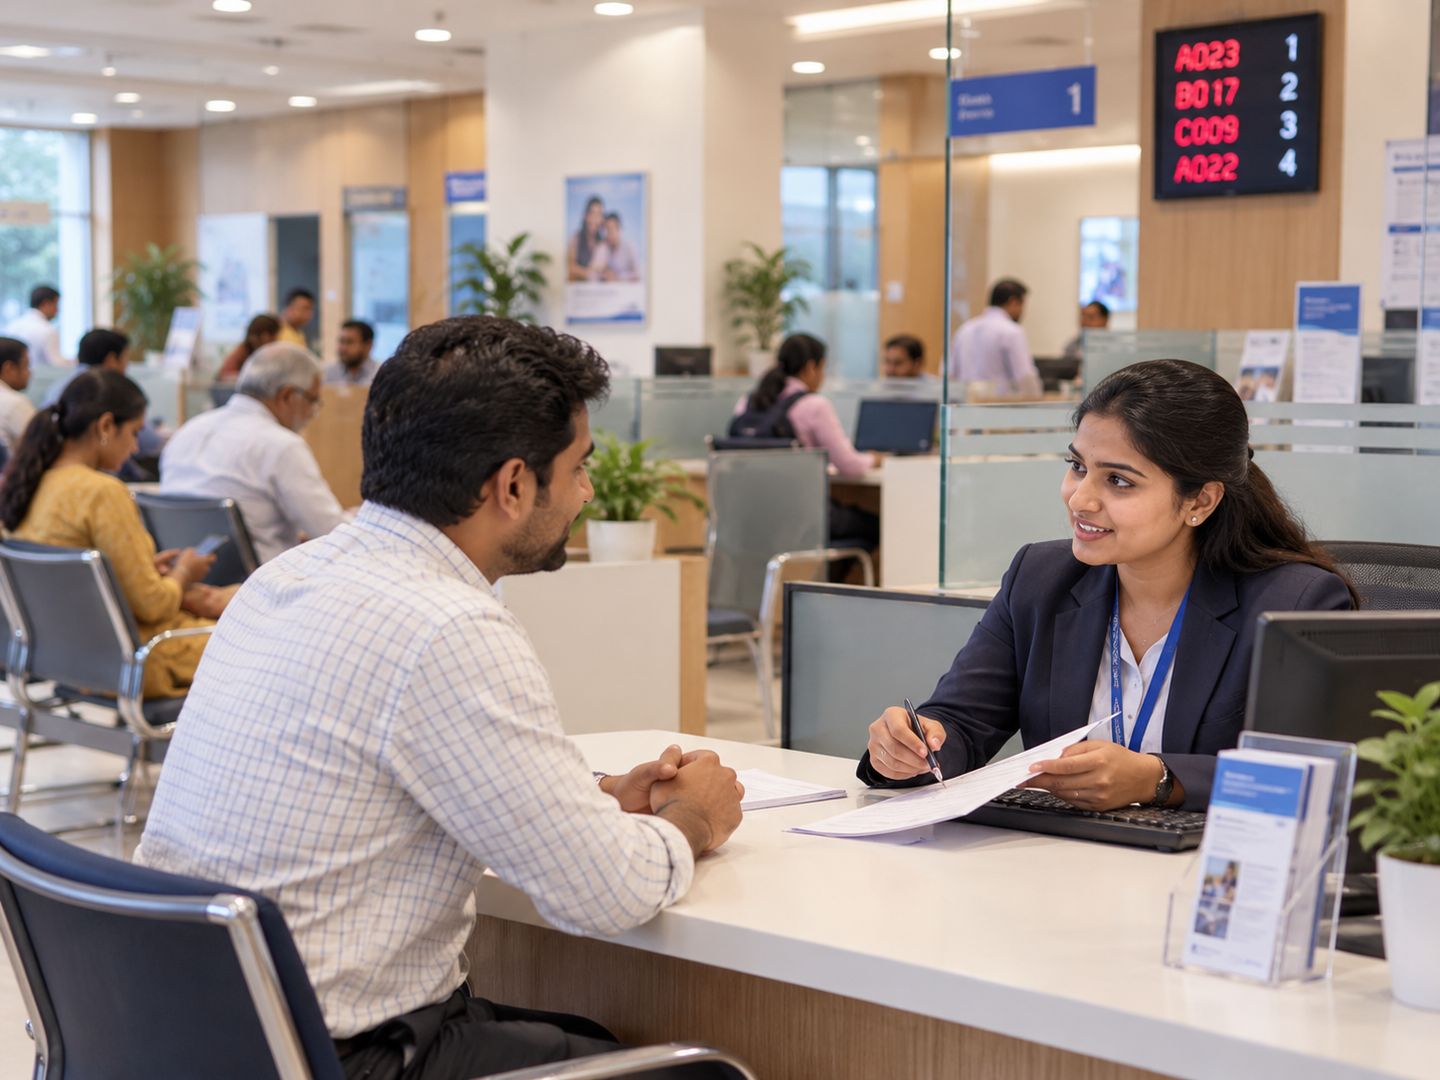
Banking is built on trust, and trust is built one interaction at a time. A customer who walks into a branch to open an account, ask about a loan or update their KYC is forming an opinion of the bank with every minute they spend there. Mystery shopping lets banks see those minutes clearly.
Why banks use mystery shopping
Banks typically use mystery shopping for three reasons:
-
Service consistency. Large networks need to know that every branch delivers the same standard of service.
-
Sales quality. Banks want to confirm that products are explained accurately, that the right product is offered to the right customer, and that there’s no mis-selling.
-
Compliance. Mandatory disclosures, fair practice codes and grievance redressal information all need to be visible and followed in practice.
Inside a typical branch mystery shop
Here’s what a single visit might look like for a savings account enquiry:
-
Arrival: The shopper notes branch cleanliness, signage, the availability of forms, and whether mandatory notices are displayed.
-
Waiting: Time to be acknowledged and time to be served are recorded.
-
Interaction: The shopper asks about opening an account. They observe whether the staff member asks about their needs, explains account variants, minimum balance and charges, and mentions digital banking.
-
Cross-sell: Was a relevant product offered? Was it explained fairly?
-
Closure: Did the staff member share contact details, explain next steps or offer to help further?
-
Narrative: Right after the visit, the shopper writes a short account in their own words, which often reveals what a checklist can’t.
Beyond the branch
Customers rarely stick to one channel. A full banking programme often includes phone banking calls, digital journeys like applying for a credit card online, and even ATM and doorstep service checks. Comparing results across channels shows where the experience is consistent and where it falls apart.
What banks do with the results
The most useful reports go beyond scores. They show patterns across regions and branch types, identify the specific behaviours that drive the biggest differences, and recommend targeted actions. Typical outcomes include refresher training for specific product conversations, updates to branch display standards, process changes in account opening, and recognition for branches that consistently excel.
A note on fairness
Branch staff work under real pressure. Good mystery shopping programmes are designed to improve systems, not to catch people out. Sharing results openly, recognising strong performers and focusing on coaching builds support for the programme across the network.
Getting started
Banks often begin with a pilot across a representative set of branches and one or two key products. The pilot sets the baseline, refines the questionnaire, and builds internal confidence before a full rollout.
Want this evidence for your brand? Talk to our team about a study scoped to your customers, channels and goals, or write to growth@bridgeloyalty.com.